This strategic mandate aims to prevent the social and economic paralysis that typically follows when digital payment networks face unexpected disruptions. As European nations continue to phase out physical currency in favor of digital convenience, the reliance on a stable internet connection has become a single point of failure for the entire economy. The transition toward a cashless society has been swift, yet the underlying infrastructure has not always kept pace with the requirements for absolute uptime. Mastercard’s decision to enforce offline capabilities across all European terminals and cards by 2027 serves as a recognition that the financial system must function as a utility, similar to water or electricity. In an era where cyber threats and weather patterns pose constant risks to telecommunications, the ability to process a transaction without a real-time handshake with a remote server is no longer a luxury but a fundamental necessity for maintaining public order and consumer confidence.
Addressing Vulnerabilities: Lessons From Infrastructure Blackouts
The impetus for this continent-wide policy was the massive energy grid failure that struck Spain and Portugal in 2025, revealing the extreme fragility of a digitized marketplace. During that event, over 55 million people were suddenly unable to buy basic necessities because payment terminals could not connect to banking clouds. Retailers were forced to shutter their doors, and a wave of panic ensued as the lack of cash left citizens without a fallback mechanism. This incident underscored that a digital-only economy is vulnerable to systemic collapse during power outages or regional network blackouts. By setting a deadline for new card issuances in early 2027 and requiring terminal updates shortly thereafter, Mastercard is positioning itself as a provider of resilient infrastructure rather than just a payment processor. This timeline reflects an urgent push to ensure that the European continent is better prepared for the next inevitable disruption to its digital connectivity.
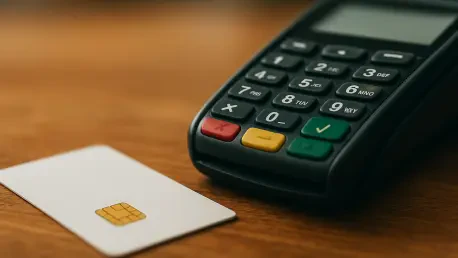
Technically, the system hinges on a paradigm shift where the card’s EMV chip acts as a local authorization vault rather than a simple data carrier. A pre-set spending limit, currently capped at €200, is stored directly on the physical card, allowing the merchant’s terminal to verify the transaction “at the edge” without an active internet link. When a customer inserts their card into an offline terminal, the two devices communicate locally to confirm the PIN and ensure the transaction falls within the authorized limit. The terminal securely stores the transaction data and uploads it to the banking network once the connection is restored. This €200 threshold is a carefully calculated figure, designed to be high enough for critical purchases like a full tank of fuel or a week’s worth of groceries, while remaining low enough to limit the total financial exposure if the card is used improperly before the bank can sync with the merchant’s local storage.
Strategic Autonomy: The Nordic Model and Geopolitical Risks
The feasibility of this rollout is supported by successful pilot programs conducted across Denmark, Latvia, and Estonia between 2024 and 2026. These nations, which are among the most cashless in the world, have already designated their payment systems as critical national infrastructure. Given their proximity to geopolitical tensions and the documented risks to undersea data cables, these governments recognized early on that a network failure could effectively freeze their national economies. The Baltic trials proved that offline chip-and-PIN functionality could keep the wheels of commerce turning even when external communications were severed. These regions provided the blueprint for the broader European mandate, demonstrating that the technical hurdles of local authorization are manageable when backed by clear regulatory support. This approach transitions the payment network from a service to a safety net, ensuring that regional instability does not translate into local financial paralysis.
However, the shift toward offline commerce necessitates a social contract between financial institutions and the public regarding the management of fraud. In a standard online environment, banks use real-time artificial intelligence to detect and block suspicious transactions instantly. Moving to an offline model removes these defenses, as a terminal cannot know if a card was reported stolen only moments before the transaction occurred. Banks and card issuers are essentially agreeing to absorb a higher degree of immediate risk to ensure societal stability during a crisis. This vulnerability will likely encourage organized crime syndicates to exploit the €200 limits during periods of known network instability. To counter this, financial institutions are now pivoting their resources toward advanced post-transaction analysis and machine learning tools. These systems are designed to identify patterns of abuse and recover losses once the network is back online, shifting the focus to detection.
Economic Transformation: Challenges for Fintech and Sovereignty
The 2027 mandate also brings the issue of European strategic autonomy to the forefront of financial policy debates. Because Mastercard and Visa process the vast majority of transactions within the eurozone, the continent’s emergency financial resilience is effectively being managed by private American corporations. This reality has accelerated the European Central Bank’s efforts to develop a sovereign Digital Euro, which would feature built-in offline capabilities independent of foreign networks. Furthermore, the mandate places immense pressure on fintech firms that have traditionally prioritized lean, cloud-first operations. These companies now face significant capital expenditures to upgrade their digital architectures and card fleets to meet the new technical standards. While established legacy banks may find the transition easier due to their deeper resources, smaller fintech startups must now navigate a more complex regulatory landscape where resilience is a core feature, potentially leading to industry consolidation.
Ultimately, the path toward the 2027 deadline required a fundamental reimagining of how digital money interacts with the physical world. Financial institutions that successfully navigated this transition focused on dual-pathway authorization models and updated their risk profiles to account for delayed transaction settlement. Moving forward, the industry prioritized the development of enhanced encryption for stored chip limits and invested in terminal hardware that could withstand extended periods of isolation. Regulators established clearer guidelines for liability in cases of systemic outages, ensuring that merchants were protected when acting in good faith. These steps transformed the European payment landscape into a hardened ecosystem capable of surviving modern infrastructure threats. For banks and merchants alike, the key takeaway involved the necessity of prioritizing technical redundancy over pure speed. By treating the payment network as a vital utility, stakeholders ensured that the basic mechanisms of commerce remained functional.