The ability to dispute fraudulent transactions through a bank provides a layer of consumer protection that is completely non-existent when dealing with cash. This fundamental advantage serves as the catalyst for a broader shift toward digital literacy and fiscal responsibility in the current economy. Beyond basic protection, these accounts function as a central nervous system for one’s economic life, coordinating the flow of wages into organized silos of spending and obligation. In a landscape where speed and precision are paramount, the checking account stands as a highly mobile repository, distinct from the static nature of long-term investments. It facilitates immediate access to liquid assets while simultaneously recording every move for later analysis. By centralizing these activities, users gain a transparent view of their financial health, allowing for adjustments to be made in real-time rather than at the end of a billing cycle when it might be too late to correct wasteful habits.
Mastering Daily Cash Flow and Digital Access
Consolidating Income: The Centralization of Spending Tools
The primary utility of a modern checking account lies in its role as a high-velocity hub for all incoming and outgoing capital. By establishing a single point of entry for income, typically through electronic direct deposits, individuals eliminate the friction associated with physical checks and waiting periods. This immediate availability of funds allows for a more responsive approach to financial obligations, ensuring that money is positioned exactly where it needs to be the moment it is earned. Moreover, the integration of debit cards and automated teller machine access provides a seamless bridge between digital balances and physical commerce. Whether settling a monthly mortgage payment or handling a spontaneous retail purchase, the account provides a standardized method of execution. This level of consolidation reduces the cognitive load of managing multiple payment sources, as every transaction is funneled through a single ledger that reflects the true state of available resources at any given time.
Transitioning from a manual cash-based system to a centralized banking platform offers a unique historical perspective on personal spending trends. With every purchase recorded digitally, the account serves as an automated diary of consumer behavior, highlighting patterns that might otherwise go unnoticed. This visibility is essential for maintaining a disciplined budget, as it allows users to categorize expenditures into essential and discretionary buckets with minimal effort. The account acts as the foundation upon which all other financial goals are built; without a clear understanding of daily cash flow, long-term saving or investing remains an uphill battle. By utilizing the checking account as a clearinghouse for all economic activity, individuals can ensure that their spending aligns with their broader priorities. This structural organization provides the clarity needed to make informed decisions about large purchases or debt reduction strategies, turning a simple deposit account into a powerful instrument for strategic fiscal oversight and control.
Digital Interfaces: The Evolution of Mobile Account Management
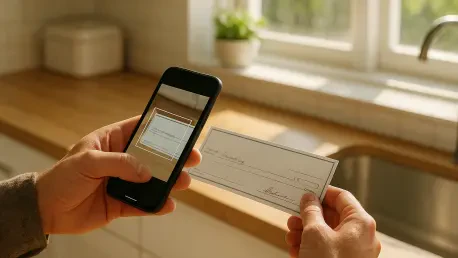
Technological advancements in 2026 have redefined the checking account, moving it from a static balance sheet to an interactive digital experience. Modern mobile applications now offer a suite of features that provide users with unprecedented control over their funds from any location. Remote deposit capture technology has essentially turned every smartphone into a personal bank branch, allowing for the instantaneous processing of paper checks through simple imaging. Furthermore, real-time notifications and balance alerts serve as a constant guardian against overspending, providing immediate feedback whenever a transaction occurs. This immediate synchronization ensures that the user is never operating on outdated information, which is a common pitfall in traditional bookkeeping. These apps also facilitate complex internal transfers between sub-accounts, making it easier to move money between spending and short-term reserves. The result is a highly responsive system that adapts to the fast-paced nature of contemporary financial life.
Beyond individual management, the integration of peer-to-peer payment protocols directly into checking platforms has revolutionized social and professional commerce. Services like Zelle or similar bank-integrated tools allow for the immediate transfer of funds without the need for third-party intermediaries or the delays associated with traditional wire transfers. This functionality is particularly useful for splitting household expenses, paying service providers, or handling small business transactions on the fly. Because these transfers are tied directly to a verified checking account, they benefit from the same institutional security and oversight as any other banking activity. This ecosystem effectively eliminates the need for carrying physical currency, which is increasingly viewed as a liability in a world optimized for digital speed. As these platforms continue to evolve, they are becoming even more intuitive, offering predictive analytics that suggest the best times to move money or pay certain bills based on historical data, further enhancing the user’s overall financial agility.
Enhancing Protection and Fiscal Efficiency
Security Frameworks: Protecting Assets Through Federal Insurance
One of the most compelling reasons to maintain a significant portion of liquid assets in a checking account is the robust safety net provided by federal regulatory bodies. In the United States, deposits are typically insured up to $250,000 by the Federal Deposit Insurance Corporation or the National Credit Union Share Insurance Fund. This guarantee provides a level of certainty that is unattainable through private storage or cash holdings, ensuring that personal wealth remains secure even in the face of institutional instability. Furthermore, banks employ sophisticated encryption and multi-factor authentication protocols to prevent unauthorized access to digital portals. These layers of defense are constantly updated to combat emerging cyber threats, representing a proactive approach to asset protection. By placing funds within this regulated environment, consumers mitigate the risks of theft, fire, or loss that are inherent to physical currency. This institutional backing allows for peace of mind, knowing that the primary vehicle for daily living is fortified by national economic safeguards.
In addition to institutional security, the transactional protections offered by checking accounts serve as a critical defense against modern fraud and identity theft. If a debit card is compromised or an unauthorized electronic transfer occurs, the account holder has specific legal rights and bank-provided tools to rectify the situation. Most institutions allow users to freeze their cards instantly via a mobile app, preventing any further damage while an investigation is conducted. The ability to dispute charges and potentially recover stolen funds provides a safety cushion that cash simply cannot replicate. Moreover, many banks now utilize artificial intelligence to monitor spending patterns and flag suspicious activity before the customer is even aware of a potential problem. This proactive monitoring acts as a silent partner in financial management, identifying anomalies that could indicate a breach. This comprehensive security architecture ensures that while money remains highly mobile and accessible, it is simultaneously shielded by a complex web of technological and legal protections.
Operational Efficiency: Automating Obligations and Wealth Building
Automation is perhaps the most transformative feature of a modern checking account, allowing individuals to streamline their financial obligations with minimal manual effort. By setting up recurring bill payments for utilities, insurance, and loan installments, users can ensure that every commitment is met on time, every time. This consistency is vital for maintaining a strong credit score, as payment history is a primary factor in credit evaluation models. Beyond credit health, automation removes the stress of tracking multiple due dates and manually processing payments each month. This “set it and forget it” approach frees up mental energy for more complex financial planning while reducing the risk of late fees or service interruptions. As the account handles the mundane tasks of debt settlement and expense management, the user can focus on long-term strategy rather than tactical execution. This shift from manual to automated management marks a significant milestone in achieving a sophisticated and efficient personal financial ecosystem.
Strategic financial management also involves using a checking account to facilitate the “pay yourself first” philosophy through split-deposits. By directing a portion of a paycheck to go straight into a savings or investment account before the remainder hits the checking balance, individuals create a forced savings mechanism that operates in the background. This ensures that wealth building happens consistently and is not dependent on what remains at the end of the month. Furthermore, the ability to link the checking account to various investment platforms allows for the seamless movement of capital into growth-oriented assets. This fluid connectivity between the transactional hub and the growth vehicles is essential for holistic financial health. By treating the checking account as a launchpad for broader goals, users can systematically build an emergency fund, save for major milestones, and contribute to retirement plans without having to initiate each transfer manually. This level of operational efficiency transforms the account from a simple spending tool into a vital engine for long-term prosperity.
Strategic Selection and Optimization
Cost Management: Navigating Fee Structures and Overdraft Rules
Navigating the various fee structures associated with checking accounts is a critical component of effective financial oversight. While many institutions offer “free” checking, these accounts often come with specific requirements such as maintaining a minimum daily balance or receiving a certain amount in monthly direct deposits. Failure to meet these criteria can result in monthly maintenance fees that slowly erode an account balance. Additionally, out-of-network ATM fees and charges for paper statements can add up over time if not managed carefully. A savvy consumer should evaluate these costs against the utility provided by the bank, seeking out institutions that align with their specific usage patterns. For instance, those who frequently travel might prioritize an account that offers ATM fee reimbursements, while others might look for banks with zero-fee structures for students or seniors. By understanding the fine print of a deposit agreement, an individual can ensure that they are not paying unnecessary premiums for basic banking services, thereby maximizing the efficiency of every dollar.
Overdraft protection represents another vital area of strategic management within the checking environment. An overdraft occurs when a transaction exceeds the available balance, and while many banks have moved toward more consumer-friendly policies, others still impose significant penalties for these occurrences. Establishing an overdraft protection link—where funds are automatically drawn from a connected savings account or a small line of credit—can prevent transactions from being declined and avoid the steep fees associated with non-sufficient funds. This safety net provides a buffer against timing errors, such as when a bill is processed before a paycheck is deposited. Understanding how these systems work allows for a more confident approach to daily spending, as the risk of a technical shortfall is mitigated. By proactively managing these settings and opting for accounts with low or no overdraft fees, users can maintain greater control over their liquidity without the fear of unexpected costs. This proactive stance on fee management is a hallmark of sophisticated financial planning in the current banking landscape.
Portfolio Optimization: Balancing Liquidity and Long-Term Growth
Achieving optimal financial health requires a clear distinction between the roles of checking and savings accounts within a broader portfolio. The checking account is designed for maximum liquidity, serving as the tool for immediate expenses, whereas savings accounts are intended for later goals and often offer higher interest rates. Keeping too much money in a checking account can be a missed opportunity, as these accounts typically offer little to no annual percentage yield. Conversely, keeping too little can lead to liquidity crises or the need to transfer funds frequently from less accessible accounts. A successful strategy involves maintaining a buffer in the checking account that covers one to two months of living expenses, while routing the surplus into high-yield savings or investment vehicles. This balance ensures that day-to-day needs are met without friction while simultaneously allowing the bulk of one’s wealth to grow through interest or capital appreciation. Mastering this delicate equilibrium is essential for anyone looking to optimize their personal balance sheet.
Selecting the right account also involves an assessment of individual habits and technological preferences. Some users may find value in interest-bearing checking accounts if they habitually maintain high balances, as this allows their liquid funds to generate a small return. Others might prioritize rewards checking accounts that offer cash back or points for debit card purchases, effectively turning daily spending into a source of passive income. The choice between a large national bank with an extensive branch network and an online-only bank with higher interest rates and lower fees depends on how much one values in-person service versus digital efficiency. In 2026, many consumers have opted for a hybrid approach, using a traditional bank for cash deposits and local services while maintaining a digital account for their primary transactional needs. By carefully matching the features of a checking account to one’s specific lifestyle and financial goals, the account ceases to be a mere repository and becomes a customized tool that enhances every aspect of an individual’s monetary management and future planning.
Strategic Directions for Financial Advancement
The successful integration of a checking account into a daily routine proved to be a decisive factor in achieving long-term fiscal stability. Those who utilized these tools effectively moved beyond simple transaction tracking and embraced a more proactive approach to money management. By prioritizing security features and automating recurring obligations, individuals created a resilient framework that protected their assets while maximizing their time. The transition toward a digital-first banking strategy allowed for more precise control over cash flow, ensuring that every dollar was accounted for and properly allocated toward specific goals. Moving forward, the most effective next step involved a comprehensive review of existing fee structures to eliminate unnecessary costs. This was coupled with the implementation of automated savings transfers, which solidified the habit of wealth accumulation. Ultimately, the disciplined use of a checking account transformed it from a basic utility into a strategic asset that supported broader economic ambitions and provided a clear path toward future financial independence.