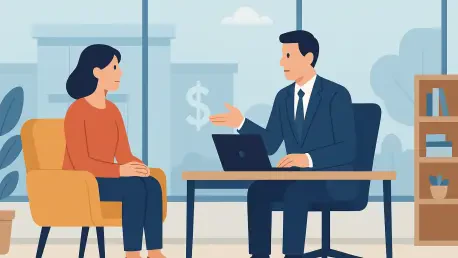
The rapid acceleration of financial technology has transformed the traditional bank branch from a bustling center of commerce into a quiet sanctuary for complex advisory services. Today, the majority of retail transactions occur within the digital realm, facilitated by high-speed interfaces and immediate settlement systems that have rendered the classic physical ledger nearly obsolete. This transformation is not merely a matter of convenience; it represents a fundamental shift in how society perceives value and security in an increasingly paperless economy. While the convenience of mobile applications allows for instant fund transfers and real-time account monitoring, it simultaneously creates a stark divide between various segments of the population. For younger individuals who have matured in a digital-first environment, the idea of visiting a physical branch for a routine balance inquiry or a simple domestic transfer seems like an inefficient relic of a bygone era. However, this tech-heavy landscape often overlooks those who rely on face-to-face interaction to navigate the complexities of personal finance and wealth management. The digital divide remains a significant hurdle, as access to technology does not always equate to the literacy required to manage assets safely.
Navigating the Generational Shift: Convenience Versus Connection
The transition toward automated services has undeniably streamlined the banking experience for millions, yet it reveals significant variations in consumer behavior across different age groups and technical backgrounds. For tech-savvy professionals, the ability to manage an entire portfolio from a smartphone during a morning commute is the ultimate hallmark of efficiency. These users prioritize speed and availability, often viewing human intervention as a potential bottleneck rather than a helpful resource. Conversely, elderly customers and those less comfortable with modern interfaces frequently find the lack of a physical presence to be a source of anxiety and confusion. For these individuals, the “human touch” provides a level of reassurance that an algorithm or an automated chatbot cannot replicate. The physical branch serves as a hub where technical assistance is provided alongside emotional support, ensuring that no segment of the population is left behind as the industry moves toward total digitization.
Building on this demographic discrepancy, it is essential to recognize that widespread smartphone adoption does not automatically correlate with high levels of digital financial literacy. Even in regions where mobile device penetration is nearly universal across all socioeconomic levels, many users still struggle with the nuances of secure digital navigation. This creates a dangerous environment where individuals may possess the tools for banking but lack the necessary skills to identify sophisticated phishing attempts or fraudulent messages. Professional bank staff play a critical role in bridging this gap by educating clients on safety protocols and providing a physical point of contact when things go wrong. Without the guidance of trained personnel, the risk of financial loss due to accidental engagement with malicious software increases significantly. Therefore, the branch remains a necessary educational center that empowers customers to use digital tools more effectively while maintaining a safety net for those who are most vulnerable to the darker side of technological progress.
The Phygital Paradigm: Future Directions for the Banking Industry
The evolution of the banking sector eventually reached a point where the distinction between physical and digital services blurred into a hybrid model known as phygital banking. This approach successfully integrated the speed of automated tools with the specialized knowledge of human professionals to create a more holistic service environment. Organizations that thrived in this environment prioritized the development of intuitive digital interfaces while simultaneously reimagining the purpose of their physical locations. Rather than viewing branches as simple transaction centers, forward-thinking institutions converted these spaces into financial wellness hubs where customers received high-value advice and technical training. This strategy ensured that the bank remained relevant to both the digital-native generation and those who required more personalized assistance. By focusing on the unique strengths of both humans and machines, the industry moved toward a more inclusive future where technology enhanced rather than replaced the fundamental human connection required for financial security.
Successful financial institutions were those that recognized the necessity of continuous education and proactive security measures within their digital frameworks. These banks implemented comprehensive digital literacy programs that targeted vulnerable demographics, effectively turning their branches into classrooms for the modern age. They also refined their automated systems to flag suspicious behavior with greater accuracy, while maintaining a dedicated team of human experts to handle the subsequent resolution process. To remain competitive, it became essential for banks to invest in advanced training for their staff, shifting the workforce away from administrative duties and toward specialized advisory roles. This transition allowed for a more efficient allocation of resources, where technology handled the mundane and humans managed the meaningful. Ultimately, the long-term sustainability of the banking sector depended on the ability to maintain trust through a balanced ecosystem that respected the diverse needs of its entire customer base, ensuring that the “human touch” remained a cornerstone of financial service delivery.