By refusing to move insurance medical records and core banking ledgers to the public cloud, BNP Paribas has drawn a definitive hard line regarding data sovereignty. This strategic decision serves as the cornerstone of a transformative five-year agreement with Google Cloud that is already redefining the boundaries of financial technology in 2026. While many institutions spent the early part of the decade experimenting with localized large language models, this partnership signals a move toward deep, structural integration of generative systems into the very fabric of high finance. As Europe’s largest bank by total assets, BNP Paribas is not merely purchasing a service but is co-authoring a blueprint for how a global systemically important financial institution can survive and thrive in an era of autonomous software. The deal focuses heavily on the deployment of Gemini Enterprise, a platform that moves beyond the simple question-and-answer format of early chatbots and instead introduces “agentic” AI capable of executing complex, multi-step professional workflows with minimal human oversight. This landmark agreement reflects a nuanced dual strategy: an aggressive embrace of Google’s Gemini infrastructure paired with a conservative “zero-trust” data policy. The bank aims to harness the immense computational power of the public cloud while keeping its most sensitive information isolated. This hybrid approach addresses the industry-wide challenge of balancing technological evolution with the strict regulatory requirements of modern high finance. By establishing these boundaries early, BNP Paribas ensures it can innovate without compromising the foundational trust of its global client base.
Part 1: Revolutionizing High-Value Banking Operations
The Implementation: Deploying Agentic AI Across Core Business Sectors
The integration of agentic AI within the bank’s core business sectors marks a departure from traditional automation toward a model of collaborative intelligence. In the realm of corporate credit memos, Gemini-powered agents are now tasked with the labor-intensive initial phase of report generation. These agents possess the capability to ingest and synthesize thousands of pages of financial statements, local macroeconomic indicators, and historical credit performance data to draft a comprehensive baseline document. This shift does not replace the human analyst but rather elevates their role within the organization. By removing the burden of manual data synthesis and formatting, the bank allows its specialists to focus on high-level risk assessment and the qualitative nuances of client relationships that an algorithm cannot fully grasp. This efficiency gain is not merely about speed; it is about improving the accuracy of credit decisions by ensuring that every memo is backed by an exhaustive analysis of available data, reducing the likelihood of human oversight in the early stages of the evaluation process.
Furthermore, the expansion of these agents into broader corporate functions illustrates a calculated strategy to prioritize sectors where document density and data complexity are highest. Beyond the credit department, AI entities are being integrated into compliance and internal audit workflows, where they monitor vast streams of internal communications and transaction logs for potential irregularities. This proactive approach to internal oversight allows the bank to identify potential risks long before they manifest as systemic issues. The implementation also extends to the bank’s human resources and administrative divisions, where agents handle the complexities of multi-national regulatory filings and internal policy management. By creating a unified layer of intelligence across these disparate departments, BNP Paribas is building a more cohesive and responsive corporate structure. This internal evolution demonstrates that the greatest immediate value of generative AI in banking lies not in customer-facing interactions, but in the radical optimization of the hidden machinery that allows a global financial giant to function effectively on a daily basis.
The Workflow: Enhancing Research and Strategic Financial Structuring
In the high-stakes world of investment research and financial structuring, the partnership with Google Cloud provides a level of computational agility that was previously unattainable. AI agents specialized in market analysis now operate as a real-time extension of the bank’s research desks, processing global news feeds, alternative data sets, and satellite imagery to identify emerging market anomalies. These agents do not simply wait for a prompt; they are designed to be proactive, alerting human researchers to shifts in liquidity or unexpected volatility in niche asset classes before these trends become apparent to the broader market. This capability significantly compresses the “alpha window,” allowing the bank to provide its institutional clients with insights that are both faster and more granular than those of its competitors. The result is a research department that functions less like a traditional publishing house and more like a high-velocity intelligence agency, capable of providing constant, data-driven updates in a 24-hour global trading environment.
Simultaneously, the application of Gemini Enterprise to strategic financial structuring is solving one of the industry’s most persistent bottlenecks. The creation of complex financial products, such as bespoke derivatives or structured debt, typically involves a long, iterative process where bankers, legal experts, and risk managers manually negotiate terms and simulate various market outcomes. Agentic AI has streamlined this by running tens of thousands of market simulations in seconds, suggesting product structures that satisfy both the client’s specific hedging needs and the bank’s stringent internal capital requirements. These agents also assist in the drafting of complex legal documentation, ensuring that the final contracts are perfectly aligned with the simulated financial outcomes. This reduction in frictional time allows the bank to move from a client’s initial request to a finalized, risk-cleared product in a fraction of the time it took only a few years ago. By accelerating the delivery of tailored financial solutions, BNP Paribas is positioning itself as the primary partner for corporate clients who require rapid execution in increasingly volatile and complex global markets.
Part 2: Balancing Innovation with Data Sovereignty
The Architecture: A Hybrid Approach to Security and Privacy
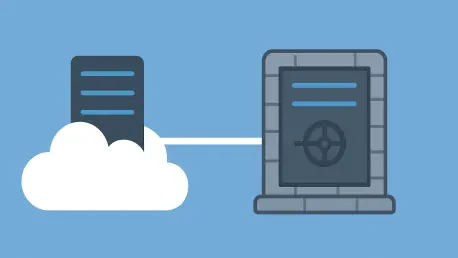
The technical architecture underpinning this deal is defined by a rigorous separation of duties between the public cloud and the bank’s private infrastructure. While the heavy computational work of training and running large-scale AI models takes place on Google’s specialized hardware, the most sensitive data remains firmly within the bank’s own physical custody. This is particularly critical for the insurance division, where the handling of medical records and private health information is subject to the world’s most stringent privacy laws. By mandating that these records never leave the bank’s on-premises servers, BNP Paribas has successfully mitigated the risk of a third-party data breach exposing deeply personal customer information. This “segmented” cloud model ensures that the AI can perform its logic-heavy tasks—such as predicting risk trends or summarizing medical histories—without the raw, identifying data ever being stored or processed on external servers that are outside the bank’s immediate physical control.
This commitment to data sovereignty extends to the core banking ledgers, which represent the ultimate record of truth for all transactions and money movements. Maintaining these ledgers on-premises is not just a security measure; it is a fundamental requirement for operational resilience. In an era where geopolitical tensions or technical failures can lead to sudden cloud service interruptions, BNP Paribas must ensure that its fundamental ability to operate as a bank remains intact regardless of the status of its technology providers. This hybrid approach allows the institution to utilize the best of what the public cloud offers—unmatched scale and AI sophistication—while retaining the security of a traditional, air-gapped financial vault for its most vital operational assets. This dual-track strategy provides a clear template for other global banks that have previously been hesitant to embrace the cloud, proving that it is possible to modernize the technological stack without surrendering control over the “crown jewels” of the business.
The Governance: Mandatory Controls and Model Integrity
To ensure the integrity of its proprietary intelligence, the bank has secured a categorical “no-training” mandate within its agreement with Google Cloud. This legal and technical barrier prevents the data processed by the bank’s AI agents from being used to tune or refine Google’s foundational Gemini models, ensuring that BNP Paribas’s unique institutional knowledge does not inadvertently benefit its competitors. This protection of intellectual property is essential in a landscape where a bank’s proprietary data is its most valuable asset. Every AI agent deployed under this partnership operates within a “sandboxed” environment where its access to data is governed by a strict “least-privilege” model. A research agent, for instance, has no technical ability to access the data utilized by a credit memo agent, and a trading agent cannot view personal customer information. This granular control over data access ensures that even as the bank becomes more interconnected through AI, the risk of internal data leaks or unauthorized cross-departmental access is effectively eliminated.
Furthermore, the bank has implemented an exhaustive audit and logging system that tracks every decision and data access made by an AI agent. In the event of a regulatory inquiry or an internal review, the bank can provide a complete “paper trail” showing exactly what information an agent accessed and the logical steps it took to reach a particular conclusion. This level of transparency is critical for maintaining the trust of regulators, who are increasingly wary of “black box” systems in the financial sector. By treating every AI agent as a distinct, auditable entity—similar to how it would treat a human contractor—the bank ensures that it remains fully accountable for the outcomes generated by its technology. This governance framework transforms AI from a potential liability into a structured and controlled asset. It reflects a mature understanding that the successful integration of AI into banking is not just a technical challenge, but a regulatory and ethical one that requires constant, high-fidelity oversight to ensure that the technology remains aligned with the bank’s long-term stability and reputation.
Part 3: Market Dynamics and the Future of Financial AI
The Landscape: Competitive Positioning in a Maturing Cloud Market
The partnership with BNP Paribas represents a significant strategic victory for Google Cloud in the ongoing battle for dominance among global technology providers. For years, Microsoft Azure held a firm grip on the corporate banking sector due to its historical integration with ubiquitous office productivity tools and its early lead in the generative AI space. However, Google is now successfully differentiating itself by focusing on the “agentic” capabilities of its Gemini Enterprise platform and the superior performance of its proprietary Tensor Processing Units. These custom chips are specifically designed to handle the massive parallel processing requirements of modern AI models more efficiently than general-purpose hardware. By offering a vertically integrated stack—where the hardware, the foundational models, and the agent-building tools are all optimized for one another—Google is providing a level of performance that is particularly attractive to financial institutions dealing with high-velocity data and complex risk simulations.
This competitive shift is forcing other major providers, such as Amazon Web Services and Microsoft, to accelerate the development of their own sovereign cloud and hybrid infrastructure tools. As more global banks look to the BNP Paribas model as a reference point, the industry is seeing a move away from generic cloud services toward highly specialized, industry-specific offerings. These “financial clouds” must provide not only massive scale but also the specific governance, security, and compliance tools required by the world’s most heavily regulated institutions. The result is a more diverse and mature ecosystem where banks have greater leverage to demand specialized terms and physical data residency options. This maturation of the cloud market is a critical development for the financial sector, as it reduces the “concentration risk” associated with relying on a single provider and allows for a more resilient global financial infrastructure that is better equipped to handle the demands of the next decade of technological evolution.
The Horizon: Regulatory Evolution and the Rise of Digital Workers
As the deployment of AI agents becomes more widespread, the regulatory landscape is beginning to shift from a focus on general data security to the specific oversight of autonomous behavioral ethics. Regulators are increasingly concerned with how AI agents make decisions in high-stakes environments like lending and trading, and they are demanding proof that these systems do not inadvertently introduce bias or systemic risk. The European Banking Authority and other global bodies are currently drafting frameworks that will require banks to demonstrate “meaningful human oversight” for all autonomous workflows. BNP Paribas’s proactive approach to logging and audibility positions it well for this new regulatory environment, as it can already provide the level of transparency that oversight bodies are expected to demand. This shift marks the end of the “experimental” phase of AI in banking and the beginning of a period where the technology will be judged by the same rigorous standards as any other critical institutional function.
Looking further ahead, the successful integration of AI agents is leading to a fundamental rethink of the banking workforce and the concept of the “digital worker.” In the coming years, the distinction between a software tool and a professional collaborator will continue to blur, as agents take on more significant roles in the institutional decision-making process. This does not necessarily lead to a reduction in headcount, but it does require a radical upskilling of the human workforce, who must now manage and oversee complex networks of AI entities. The future of banking will likely be defined by “hybrid teams” where human expertise in relationship management and ethical judgment is amplified by the computational speed and data-processing power of AI agents. As this transition matures, the primary competitive advantage for a bank will no longer be its size or its traditional assets, but its ability to effectively govern and utilize this new digital labor force to deliver superior value to its clients in an increasingly automated world.
Final Considerations: Navigating the Era of Sovereign Intelligence
The strategic alliance between BNP Paribas and Google Cloud established a clear precedent for the future of the global financial industry. By successfully decoupling the analytical power of artificial intelligence from the physical location of sensitive data, the bank proved that the choice between innovation and security was a false dichotomy. Financial institutions that examined this model recognized that the path forward required a radical transparency with regulators and a deep investment in hybrid infrastructure. The focus shifted from merely adopting tools to building robust governance frameworks that ensured AI agents remained accountable and auditable at every stage of their lifecycle. Leaders in the sector began prioritizing the creation of “sovereign intelligence” centers, where the benefits of global technology were harvested within the safety of highly controlled, localized environments. It became evident that the primary challenge for the coming years would not be the availability of AI models, but the organizational ability to integrate them into existing human workflows without introducing systemic fragility. This partnership ultimately provided a masterclass in how to modernize the banking core while maintaining the absolute integrity of the institution’s most vital assets, ensuring that technology served as a shield for the bank’s reputation rather than a risk to it. Moving forward, the success of such initiatives will depend on the continuous evolution of “human-in-the-loop” systems that can maintain oversight as the complexity of agentic behavior grows.