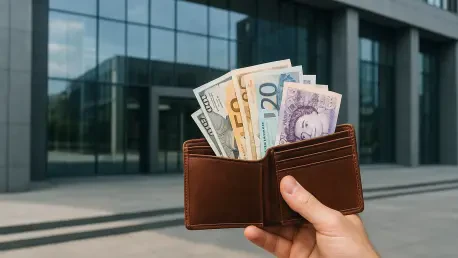
Nigerian regulators are tightening oversight of the foreign exchange market to eliminate restrictive practices that prevent citizens from utilizing their own foreign currency savings. This move comes amid a surge of complaints from depositors who find themselves unable to access funds stored in domiciliary accounts. While the banking sector has seen various reforms from 2026 to 2028, the persistent friction between financial institutions and their clients regarding hard currency remains a critical hurdle for economic stability. The Central Bank of Nigeria has noted that these bottlenecks often manifest as arbitrary withdrawal limits or outright denials of service. By launching a full-scale inquiry, the apex bank aims to identify whether these restrictions stem from genuine liquidity shortages or are strategic maneuvers by commercial entities to manage their own currency risks at the expense of the public. This represents a pivot toward more aggressive consumer protection for all.
Market Friction and Non-compliance
The core of the current investigation involves a series of practices that the central bank views as potential impediments to the timely fulfillment of withdrawal requests. Across major financial hubs like Lagos and Abuja, customers have reported a disturbing lack of consistency in how banks handle foreign currency transactions. Some individuals were informed that US Dollars and British Pounds were entirely unavailable for withdrawal, while others sitting in the same waiting area were offered only small denominations that are difficult to use in international commerce. These discrepancies suggest a lack of transparent allocation protocols within the banking halls. Furthermore, some tellers have reportedly claimed a complete lack of physical cash even as high-net-worth individuals were seen completing significant transactions. Such anecdotal evidence has fueled public anxiety and prompted the regulator to examine the digital ledgers versus the actual physical holdings of these banks.
Industry insiders suggest that some financial institutions might be prioritizing their own profit-generating activities over their fundamental duty to serve account holders. There is growing suspicion that banks are diverting available foreign cash to settle their own offshore obligations or to engage in speculative trading rather than meeting the immediate needs of domestic depositors. By offering inconvenient denominations or imposing sudden, unannounced caps on over-the-counter withdrawals, banks may be attempting to technically fulfill the requirement of availability while practically preventing the transaction from occurring. This subtle form of gatekeeping is particularly damaging to the reputation of the national banking system, as it creates a false impression of systemic instability. The central bank is now scrutinizing the internal correspondence of several lenders to determine if there has been a coordinated effort to withhold liquidity from the retail segment today.
Future Regulatory Oversight and Resolutions
In response to the mounting evidence of restrictive practices, the central bank is preparing to release a formal circular that will redefine the operational standards for domiciliary account management. This upcoming directive is expected to mandate that all commercial banks honor legitimate withdrawal requests without delay, provided the customers meet established regulatory requirements. To enforce this, the regulator may implement real-time monitoring tools that track foreign currency inflows and outflows at the branch level, leaving little room for discretionary denials. The intervention aims to streamline foreign exchange operations and ensure that the rights of account holders are not superseded by corporate interests. By tightening oversight and eliminating these hurdles, the authorities hope to restore trust in the formal financial sector. This shift is part of a broader trend of increased scrutiny designed to maintain liquidity and transparency within the market now.
The investigation concluded that a more rigorous framework was necessary to prevent future occurrences of currency hoarding within the private banking sector. Regulators established that clear communication and standardized withdrawal protocols were the only ways to mitigate the panic that often followed reports of cash shortages. Moving forward, financial institutions were advised to digitize their foreign currency allocation processes to provide customers with real-time updates on cash availability. This transition reduced the reliance on verbal denials from tellers and introduced a layer of accountability that was previously absent. Strategic stakeholders emphasized that maintaining a healthy reserve of physical cash was secondary to the transparency of its distribution. Future considerations involved the integration of blockchain-based tracking to ensure that every dollar entering the system was accounted for. These steps effectively shifted the burden of proof from the customer.