Traditional Irish banks are struggling to justify high account fees while their digital competitors provide sophisticated budgeting tools and seamless user interfaces for free. The financial landscape in 2026 reflects a dramatic departure from the era when a handful of institutions dictated the terms of personal finance. Consumers are no longer tethered to local branches by necessity, as the proliferation of smartphone-based banking has dismantled geographical barriers. While Allied Irish Banks and Bank of Ireland continue to serve a substantial portion of the population, the momentum has clearly shifted toward agile, tech-driven challengers like Revolut and N26. This migration is fueled by a generational demand for transparency and a refusal to tolerate the inefficiencies that once characterized the Irish banking experience. The recent widespread outages in digital systems have acted as a moment of reflection for many, forcing a serious evaluation of whether the convenience of a modern app outweighs the perceived stability of a legacy vault. This debate is now at the center of financial discussions across the country, as users weigh the risks of technical failure against the certainty of high maintenance costs and stagnant service levels.
The Financial Case for Switching
Comparing Fee Structures: Savings and Expenditures
The economic rationale for moving away from high-street banks centers largely on the persistent burden of account maintenance fees. In 2026, the notion of paying a flat quarterly or monthly fee just to keep an account open feels increasingly archaic to a population accustomed to the freemium models of the broader digital economy. Traditional pillars such as AIB have maintained fee structures that often result in customers paying roughly €72 annually before a single transaction even occurs. For a modern worker managing multiple subscriptions and digital payments, these legacy costs represent an unnecessary drain on resources. In contrast, neo-banks have capitalized on their low overhead costs to offer basic banking services without these recurring charges. By eliminating the need for expensive physical real estate and massive administrative departments, digital-first banks provide a value proposition that is difficult for incumbents to match. This cost difference is not just a minor convenience but a significant financial incentive that drives thousands of residents to migrate their primary spending accounts each month.
Beyond everyday operational costs, the disparity in interest rates has become a primary driver of the mass exodus from traditional Irish banking. While domestic pillars offer negligible returns on deposits, international neo-banks and European competitors are providing significantly higher rates, with some digital products reaching up to 3.3% as of 2026. This gap in wealth preservation potential is forcing savvy consumers to look toward digital platforms to ensure their savings are not eroded by the pressures of inflation. The frustration is compounded by the perception that Irish banks are quick to raise interest rates on loans and mortgages but remarkably slow to pass those benefits on to savers. For individuals attempting to build a deposit for a home or manage a retirement fund, the mathematical reality of neo-banking is undeniable. The ability to move funds across borders with a few taps on a screen has effectively ended the era where Irish banks could rely on customer inertia to keep low-interest deposits. Consequently, the digital migration is increasingly viewed as a necessary step for financial health rather than a mere lifestyle choice for the tech-savvy.
Operational Efficiency: The User Experience Standard
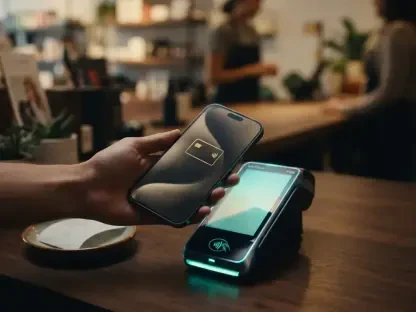
The user interface of neo-banks has set a new gold standard that traditional banks struggle to replicate despite their increased investment in digital transformation. Features such as instant spending notifications, “vaults” for automated saving, and the ability to freeze a card with a single tap provide a sense of real-time control that legacy apps often lack. For many users, the “ping” of a successful transaction on a smartphone is not just a convenience; it is a sign of a functional, modern financial life. These apps are designed with a mobile-first philosophy, prioritizing intuitive navigation and clear visual data representation. In contrast, many traditional banking apps still feel like scaled-down versions of complex desktop websites, often requiring multiple steps to perform basic tasks. The agility of neo-banks allows them to roll out updates and new features on a weekly basis, ensuring they remain at the cutting edge of consumer expectations. This technological lead has created a significant gap in customer satisfaction, as users grow accustomed to the seamless integration of their finances with their digital lives.
Furthermore, the bureaucratic “security theater” often associated with traditional banks has become a source of intense irritation for the 2026 consumer. While legacy institutions argue that their multi-layered verification processes and human interventions are necessary for safety, many users find them intrusive and counterproductive. There have been numerous reports of individuals struggling to access their own large sums of money for legitimate purchases, facing questioning from bank staff that feels more like an interrogation than a service. Neo-banks, however, tend to utilize advanced biometric authentication and AI-driven fraud detection that operates silently in the background. This approach offers a higher level of perceived freedom without sacrificing security, as users can manage high-value transactions without the need for a physical visit to a branch or a lengthy phone call to a central office. The shift from manual oversight to automated efficiency has fundamentally changed the power dynamic between the bank and the customer, placing the user back in the driver’s seat of their own financial destiny through superior technology.
Trust and the Ghost of the Financial Crisis
Historical Resentment: A Stain on Institutional Reputation
The relationship between the Irish public and traditional banks remains deeply scarred by the historical trauma of the financial crisis and the subsequent taxpayer-funded bailouts. Many citizens view AIB and BOI not as stable protectors of wealth, but as entities that fueled a destructive housing bubble and then held the national economy hostage to secure their own survival. This legacy of distrust continues to cast a long shadow over the sector in 2026, making consumers far more willing to experiment with new players in the market. There is a perceptible moral and ethical dimension to the switch, as younger generations in particular feel no loyalty toward institutions they associate with the economic hardships faced by their parents. For these individuals, moving their money to a neo-bank is a form of silent protest against a banking culture they perceive as predatory and self-serving. This lack of emotional attachment makes it easy for disruptors to gain a foothold, as they do not have to overcome a deep-seated tradition of brand loyalty.
Furthermore, the perceived lack of accountability for past failures remains a recurring theme in public discourse regarding the banking sector. While legacy banks have made efforts to improve their corporate governance and community engagement, the public memory is long and unforgiving. Every time a traditional bank announces high profits while simultaneously closing local branches or increasing fees, it reinforces the narrative of an out-of-touch institution. Neo-banks, despite their own technical challenges, are often seen as “outsiders” that are not part of the old establishment. This status allows them to present a fresh identity that is untainted by the complex political and social baggage of the domestic market. For a consumer who felt abandoned by the financial system during previous downturns, the appeal of a clean slate is powerful. The transition to digital platforms is therefore not just about better apps or lower fees; it is about seeking a financial partner that is perceived to be free from the institutional arrogance that many believe led to the previous collapse.
Redefining Reliability: Trust in the Digital Age
While traditionalists frequently argue that physical branches provide a necessary safety net, modern consumers increasingly view these stone buildings as obsolete relics of a bygone era. A common sentiment in 2026 is that a system failure at a traditional bank is just as paralyzing as an app outage, but with the added frustration of a physical door that would be locked or useless during a server crash anyway. The historical notion of trust was built on physical presence—the ability to walk in and speak to a manager—but today’s trust is built on consistent uptime, transparency, and the accessibility of funds via biometric authentication. When a neo-bank experiences an outage, it is often a national news event precisely because the service is usually so reliable and integrated into daily life. Traditional banks have also suffered from catastrophic IT failures that prevented customers from accessing funds for days at a time, yet they rarely face the same level of existential questioning as their digital counterparts. This suggests a double standard that is slowly beginning to fade as digital banking becomes the norm.
The definition of security has also evolved to focus on the speed of response rather than the thickness of the vault walls. In 2026, the ability to instantly receive an alert for a suspicious transaction and freeze the card immediately is considered a more effective form of security than traditional bank monitoring. Users value the transparency of seeing every transaction in real-time, which allows them to identify errors or fraud much faster than waiting for a monthly paper statement or checking a clunky legacy portal. This shift in perspective means that the “reliability” of a bank is now measured by its technical robustness and the quality of its software engineering. As neo-banks continue to improve their infrastructure and regulatory compliance, the argument for traditional “stability” becomes harder to maintain. The consensus among the digital-first generation is that no system is immune to failure, but the bank that provides the best tools to manage one’s money on a daily basis is the one that has truly earned their confidence and loyalty in the long term.
The Reality of Big-Boy Banking
Big-Boy Banking: Where Established Institutions Lead
Despite the massive surge in digital adoption, there remains a segment of financial activity where traditional banks are still considered a necessary fixture. For complex needs such as large-scale mortgages, significant foreign exchange requirements for businesses, or intricate credit lines, the established infrastructure of a legacy bank offers a level of perceived security that neo-banks have yet to fully match. Many Irish consumers still categorize neo-banks as “digital wallets” for pocket money and social spending rather than repositories for their entire net worth. When it comes to the most significant financial decision of a lifetime—buying a home—the familiarity of a traditional lender and the ability to navigate a complex regulatory environment can be reassuring. The Irish mortgage market is still heavily dominated by the pillars, and while neo-banks are making inroads, the process of securing a high-value loan often requires a level of human interaction and local market knowledge that a purely algorithmic approach might struggle to provide in its current state.
This lingering reliance on traditional banks for “serious” finance creates a bifurcated banking experience for many Irish residents. They may use a digital challenger for 95% of their monthly transactions but keep their salary mandate and mortgage with a high-street bank to maintain a long-term credit history. This behavior is driven by a caution that neo-banks, while convenient, might be more susceptible to sudden changes in market conditions or regulatory shifts. There is also a practical consideration regarding the “proof of funds” required for various legal and professional transactions, where a statement from a traditional bank is sometimes still viewed with more gravitas than an export from a digital app. While this perception is changing as digital-only banks obtain full European banking licenses and regulatory status, the cultural shift is slower than the technological one. For those with complex financial lives, the legacy bank remains a vital, if somewhat begrudgingly used, part of their overall wealth management strategy in the current 2026 economic environment.
Geopolitical Risks: Considering Security and Support
Critics of neo-banks often highlight potential risks regarding ownership and the perceived lack of human-led customer service during a crisis. The geopolitical origins of some neo-bank founders have been raised as a point of caution for individuals managing high-value assets or those concerned about long-term data privacy. While these platforms are heavily regulated by European authorities, the “app-only” nature of the business can feel vulnerable to external shocks that might not affect a domestic, state-supported institution in the same way. For a certain demographic, the idea that their entire financial life is controlled by a company with no physical presence in the country is a bridge too far. They worry about what happens if their account is frozen by an automated algorithm and there is no manager’s office to visit to resolve the issue. This fear of being “locked out” of one’s own life by a faceless entity remains one of the primary hurdles for neo-banks attempting to move from being a secondary card to a primary financial provider.
Furthermore, while digital apps excel at automated tasks and simple inquiries, the difficulty of reaching a human representative during a complex crisis remains a significant challenge. Traditional banks argue that their physical presence and dedicated phone lines offer a level of support that digital-only platforms cannot replicate. When a customer is the victim of a sophisticated fraud scheme or faces a complicated legal issue regarding their funds, the value of a human expert becomes apparent. Neo-banks have attempted to bridge this gap with premium subscription tiers that offer “priority support,” but the effectiveness of these chat-based systems is still a subject of debate among users. The struggle to get a clear, personalized answer from a bot can lead to immense frustration when real money is on the line. As a result, the perceived safety net of a traditional bank’s human workforce continues to be a compelling argument for those who prioritize customer service and personal accountability over the convenience and low cost of a purely digital banking experience.
Finding the Middle Ground
The Hybrid Model: Blending Tradition with Technology
The emerging consensus among Irish consumers in 2026 is not necessarily a total abandonment of traditional institutions, but rather a strategic “hybrid” approach to personal finance. By using neo-banks for daily transactions, budgeting, and travel while maintaining a legacy account for long-term credit and mortgages, users can effectively mitigate the risks of technical outages. This diversification allows individuals to enjoy the high-tech features and low fees of digital disruptors without completely cutting ties with the domestic financial infrastructure. Keeping a small balance in a traditional account provides a “Plan B” in the event of a major app failure, ensuring that essentials can still be paid for during a digital disruption. This strategy has become common practice for those who have moved past the initial excitement of neo-banking and are now looking for a balanced, sustainable way to manage their money. It represents a maturation of the consumer, who recognizes that both systems have distinct strengths and inherent weaknesses.
This hybrid model also serves as a pragmatic solution to the current limitations of both sectors. While the neo-bank provides the agility needed for the 2026 digital economy, the legacy bank provides the historical data and institutional weight required for major life milestones. Many financial advisors now suggest that having accounts with at least two different banking providers is a basic component of modern financial literacy. This prevents a single point of failure from paralyzing an individual’s entire economic life. Furthermore, having a presence in both systems allows consumers to take advantage of the best interest rates and promotional offers from both sides of the market. The competition between the old guard and the new challengers has created a buyer’s market, and the hybrid consumer is the one most likely to benefit from this rivalry. By refusing to be “loyal” to any single brand, the modern user ensures that they are always getting the best possible service and value, regardless of whether the bank is located on a street corner or in a data center.
Financial Literacy: Driving Market Evolution
The shift toward digital banking is being accelerated by a more financially literate population that refuses to accept subpar service as the status quo. As people become more comfortable moving money across borders to chase better interest rates or lower fees, the “one-bank-for-life” model is rapidly disappearing. This maturation suggests that the move toward neo-banks is a rational, permanent response to a stagnant domestic market rather than a fleeting trend driven by tech-savvy youth. In 2026, the average consumer is much more aware of the hidden costs of banking, from unfavorable exchange rates to the impact of inflation on stagnant savings. They are equipped with comparison tools and community-driven data that make it impossible for traditional banks to hide their inefficiencies. This increased transparency has forced a level of accountability that was previously absent in the Irish market, as customers are now more likely to switch providers the moment they feel their needs are not being met by their current institution.
This evolution is also reflected in how people discuss money and banking in their social circles. Financial advice that was once the domain of specialized professionals is now shared via social media and community forums, where users trade tips on which neo-banks offer the best “cashback” deals or the most robust security features. This democratization of financial knowledge has empowered individuals to take control of their assets in a way that was not possible a decade ago. The result is a more dynamic and competitive environment where banks are forced to prove their value on a daily basis. The digital-first generation is now entering its peak spending and saving years, and their expectations are fundamentally different from those of their predecessors. They view banking as a utility that should be efficient, cheap, and invisible, rather than a formal relationship with a respected pillar of society. This cultural shift is the most significant challenge facing legacy banks, as they must find a way to remain relevant to a customer base that no longer values their history or their physical presence.
Final Outlook: Navigating the New Financial Reality
Competitive Innovation: The Sector Wake-Up Call
The success of neo-banks effectively served as a profound wake-up call for the Irish banking sector, forcing incumbents to modernize their internal systems or risk total irrelevance. Throughout 2026, the pressure to innovate led to a series of significant digital upgrades within traditional institutions, as they desperately tried to match the agility of their tech-focused rivals. These legacy banks realized that their survival depended on more than just their physical footprint; they needed to offer the same level of real-time control and transparency that consumers had grown to expect. While they managed to close the gap in some areas, such as improved mobile apps and faster transfer times, the underlying complexity of their ancient IT infrastructure continued to hinder their progress. This period of intense competition ultimately benefited the consumer, as the threat of losing market share forced the old guard to be more responsive to public demands for better service. The industry reached a point where the distinction between a “tech company that banks” and a “bank that uses tech” began to blur, creating a new standard for the entire domestic market.
The rapid rise of digital challengers also demonstrated that the barriers to entry in the financial world were much lower than the traditional banks had once assumed. By focusing on niche services and superior user experiences, neo-banks proved that they could capture a massive share of the daily transaction market without the need for a full suite of traditional banking products. This forced a strategic pivot among the legacy pillars, who had to rethink their business models to compete with players that had significantly lower operating costs. Many traditional banks were pushed into streamlining their operations, which sometimes led to the closure of even more physical branches, ironically accelerating the very digital shift they were trying to manage. The resulting landscape was one where only the most adaptable institutions flourished, regardless of their age or history. The overall transformation of the sector ensured that the Irish financial system became more resilient and technologically advanced, preparing it for the even more complex challenges of the coming years.
Financial Redundancy: The Ultimate Modern Strategy
Ultimately, the most effective way for a modern consumer to navigate this changing landscape was through the implementation of deliberate financial redundancy. Maintaining a secondary card from a different provider or a small amount of cash ensured that the occasional digital outage became merely a minor inconvenience rather than a personal catastrophe. The historical transition to neo-banking revealed that while technology provided immense benefits in terms of cost and efficiency, it also introduced new types of risks that required a more sophisticated approach to personal management. Savvy users learned to treat their financial life like a critical IT system, building in backups and fail-safes to protect themselves from server crashes or regional disruptions. This proactive stance allowed them to enjoy the zero-fee benefits and high-tech tools of the disruptors while keeping a foothold in the traditional system for long-term security. The era of blind loyalty to a single institution was replaced by a more tactical and self-reliant mindset that prioritized accessibility and risk mitigation above all else.
The technological superiority and cost-effectiveness of neo-banks provided a value proposition that legacy banks, burdened by their history and high overheads, found nearly impossible to beat in the long run. As 2026 progressed, the transition toward a digital-first economy became a permanent feature of the Irish social fabric, influencing everything from how people were paid to how they saved for their future. The legacy institutions that survived were those that embraced this new reality and focused on providing high-value specialized services that apps could not yet fully replicate. For the average person, the “ping” of a smartphone notification remained the primary sound of their financial life, representing a level of freedom and control that previous generations could only imagine. The shift from tradition to utility was completed not because of a single technological breakthrough, but because of a fundamental change in what it meant to trust a financial institution in a world where data was the most valuable asset. The new financial reality required a blend of old-school caution and new-age innovation, ensuring that the consumer remained the ultimate winner in the ongoing battle for the future of money.