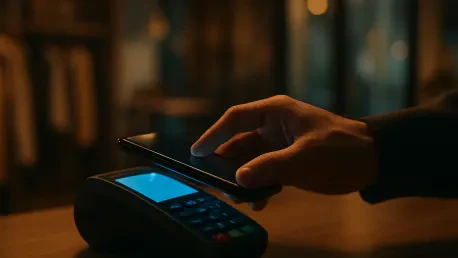
The formal consultation period regarding Apple’s contactless technology is set to run until November 17, 2026, marking a critical turning point for the future of UK mobile payments. The Competition and Markets Authority (CMA) has taken action to challenge the ironclad control Apple maintains over the Near Field Communication (NFC) hardware embedded within every iPhone. For years, the tech giant has funneled users toward its own Apple Wallet and Apple Pay services by restricting access to this essential hardware, effectively stifling competition in one of the world’s most advanced financial hubs. The new proposal seeks to mandate that Apple opens its proximity-based technology to third-party developers, including domestic banks and agile fintech startups. By doing so, regulators hope to foster a more vibrant and competitive landscape that benefits consumers and businesses alike. This move is about ensuring the UK remains a leader in global fintech innovation by breaking down artificial barriers that have historically limited market diversity and technological growth.
Addressing Structural Barriers: The Technical and Jurisdictional Hurdles
The primary obstacle identified by British regulators involves the technical exclusivity that has long defined the iPhone ecosystem. Historically, Apple has argued that keeping the NFC chip locked behind its proprietary software is a necessary measure to ensure user security and data privacy. However, the CMA has found evidence suggesting that international standards for contactless communication provide robust security without the need for such restrictive practices. This shift in regulatory perspective follows developments in the European Union, where firms like PayPal and Curve launched alternative payment solutions once given access to the underlying hardware. In the UK, the lack of such interoperability has left a gap in the market, preventing local firms from delivering the same level of seamless integration that Apple Pay currently enjoys. By demanding adherence to open international standards, the CMA aims to align the UK with global trends and adopt a more versatile payment solution for all users.
Beyond technical barriers, jurisdictional inconsistency remains a significant challenge for British businesses trying to scale their digital offerings. While European neighbors have enjoyed a more open mobile environment for several months, UK-based fintech companies have remained locked out of the iPhone’s core payment hardware. This disparity has created a two-tier market where British consumers have fewer choices than their counterparts across the English Channel. The CMA argues that maintaining these barriers is unsustainable if the UK wishes to preserve its status as a global powerhouse of financial innovation. The authority’s proposal seeks to rectify this by forcing a level of transparency that has been absent since the inception of mobile wallets. By creating a unified regulatory expectation, the government intends to facilitate a market where innovation is driven by the quality of the service rather than the ownership of the device’s physical components in a competitive landscape.
Shaping Commercial Fairness: Fees and Future Digital Infrastructure
Technical access is only half the battle; the CMA also emphasizes the need for fair and substantially lower fees for third-party providers. While the regulator is not setting specific price points, it has established principles to ensure that the cost of accessing NFC functionality does not price out independent business models. The goal is to create a balanced environment that recognizes Apple’s platform investments while ensuring that fees are low enough to allow fintech startups to flourish and offer meaningful alternatives to consumers. Lowering these financial thresholds is expected to accelerate the adoption of Open Banking initiatives, where consumers can make direct payments from their bank accounts to merchants, bypassing traditional card networks entirely. This evolution could significantly reduce transaction fees for retailers, passing those savings on to the broader public. By decoupling payment hardware from a single provider, the UK is setting a more flexible and open financial stage.
Furthermore, the commercial viability of these third-party apps depends on their ability to offer a comprehensive user experience that matches the convenience of native services. The CMA has noted that high entry fees and onerous terms of service have historically discouraged smaller firms from investing in the iPhone ecosystem. To counter this, the proposed regulatory framework focuses on ensuring that technical interoperability is commercially sustainable for diverse players. This means that banks and niche fintech providers should be able to offer loyalty programs, rewards, and integrated financial management tools without being penalized by excessive platform rents. By establishing a fairer economic foundation, the government hopes to spark a new wave of digital entrepreneurship. This approach ensures that the “brilliant British businesses” cited by regulators have a genuine opportunity to compete on merit, rather than being excluded by the sheer financial weight of a global gatekeeper.
Strategic Implementation: Actionable Steps for the Digital Era
The transition toward an open NFC ecosystem successfully opened doors for a variety of use cases that extended far beyond simple retail transactions. By dismantling the legacy barriers, the UK government allowed the iPhone to function as a universal interface for digital IDs, car keys, and sophisticated travel ticketing systems. This shift empowered local authorities and private enterprises to develop integrated solutions that enhanced the daily lives of millions of citizens. Logistics firms and hotel chains were finally able to deploy secure, proximity-based credentials without navigating the restrictive rules of a single device manufacturer. The resulting environment fostered a culture of innovation where the device served as a neutral platform for a wide array of essential services. This historical shift proved that regulatory intervention, when applied proportionately, could stimulate growth while maintaining high standards of security and reliability for every user across the nation.
In the wake of these developments, businesses were advised to review their mobile strategies to take full advantage of the newly accessible hardware features. Financial institutions and technology developers focused on building robust, interoperable applications that adhered to the latest international security protocols. Stakeholders were encouraged to collaborate on cross-industry standards to ensure that digital wallets and identification tools remained compatible across different service providers. This proactive engagement helped to solidify the UK’s position as a forward-thinking leader in the digital economy. The final assessment of the consultation feedback provided a roadmap for other nations seeking to balance tech dominance with market competition. By prioritizing consumer choice and fair access, the regulatory framework transformed the mobile payment landscape into a diverse and resilient ecosystem. This effort ensured that the next generation of fintech was built on openness.