Priya Jaiswal is a distinguished authority in the banking and financial services sector, bringing years of nuanced expertise in market analysis and portfolio management to the table. Known for her sharp insights into international business trends, she has spent her career advising institutions on how to balance aggressive growth with the foundational stability required in an ever-shifting economic climate. As we stand in 2026, the intersection of physical community presence and high-octane digital lending has become the new frontier for regional banks. Today, we delve into the strategic evolution of retail banking networks and how localized investments are being used to fuel national-scale ambitions.
In this discussion, we explore the shifting philosophy behind branch design and the move toward creating spaces that serve as both community hubs and consistent brand ambassadors. We examine the specific financial motivations behind reducing a bank’s reliance on high-cost brokered deposits in favor of building a loyal, local retail base. Additionally, the conversation touches upon the logistical hurdles of entering new, high-competition markets and the critical importance of marrying digital onboarding with the physical branch experience to ensure long-term profitability and customer retention.
How are modern banking centers evolving to balance the need for a recognizable brand identity with the unique local flavors of the communities they serve?
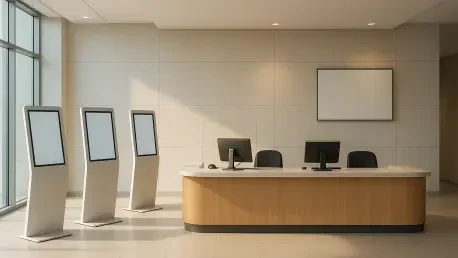
The transformation of the physical branch is one of the most exciting shifts we are seeing in 2026, moving away from the cold, transactional cubicles of the past toward what I like to call “community anchors.” For an institution like Northeast Bank, which manages $5.23 billion in assets, the goal is to ensure that whether a customer walks into a newly renovated space in Augusta or a fresh location in Bangor, the sensory experience—the lighting, the digital kiosks, the professional atmosphere—is immediately familiar. However, this brand consistency is artfully layered over the local character, such as incorporating regional architectural cues or community-specific meeting spaces that make the bank feel like a neighbor rather than a distant corporation. This “rebuild from the ground up” approach in Augusta isn’t just about fresh paint; it’s about creating a modern, welcoming environment where employees have the physical tools to support complex financial conversations. By making these spaces inviting, banks are betting that the physical environment will act as a silent but powerful recruiter for new retail deposits.
Northeast Bank has achieved remarkable success in national lending, yet there is a clear strategic push to revitalize its Maine branch network. What is the financial logic behind prioritizing retail deposits over wholesale or brokered funding right now?
The math behind this move is quite compelling when you look at the cost of capital and the health of the net interest margin. Currently, the bank holds about $1.75 billion in higher-cost brokered deposits, which are essentially wholesale funds that carry a much heavier price tag than money sitting in a local resident’s checking account. By contrast, their branch network provided approximately $1.2 billion in deposits as of mid-2025, and strengthening this retail base is the key to lifting overall profitability. When a bank can replace expensive, volatile brokered funds with stable, lower-cost retail deposits, they create a much more resilient funding foundation for their ambitious lending programs. This shift is essential for supporting their massive $1.7 billion commercial real estate portfolio and their $153 million in SBA loan originations without squeezing their margins.
Entering a major hub like Bangor is a significant move for any regional player. What are the primary challenges and rewards of establishing a de novo branch in a market where the institution may not yet have deep roots?
Expanding into a market like Bangor, which represents over $5 billion in retail deposits, is a high-stakes endeavor that requires more than just opening a door; it requires winning the “name recognition” war. As we look toward the opening of new locations in early 2027, the challenge lies in the fact that you are starting from zero in terms of local convenience and historical presence. It is often described as the hardest work a bank will ever do because you have to convince a settled community to move their financial lives to a “newcomer.” However, the reward is the ability to tap into a massive pool of core deposits that can fuel decades of future growth. By establishing a physical footprint, the bank isn’t just seeking transactions; they are looking to deepen relationships that simply cannot be replicated through a purely digital or national lending model.
With net income jumping from $83.4 million to $107.5 million in a single year, the bank is clearly “punching above its weight” in lending. How does a robust physical branch network act as a stabilizer for such high-velocity national lending operations?
High-velocity lending in sectors like commercial real estate and SBA loans is incredibly lucrative, but it creates a constant, outsized demand for reliable funding. The record-breaking $107.5 million in net income we’ve seen recently is a testament to the bank’s skill in asset generation, but that growth can be precarious if it relies too heavily on the “hot money” of the brokered market. A revitalized branch network acts as a shock absorber; it provides a steady, predictable flow of liquidity that isn’t as sensitive to the whims of national interest rate fluctuations. When the physical locations are modern and efficient, they attract the kind of long-term customers who keep their money in the bank for years, providing the stable “dry powder” needed to continue aggressive lending. It is the classic “barbell strategy” where a traditional, localized deposit franchise supports a sophisticated, national-scale credit engine.
There is frequent talk about the “marriage” of digital and physical banking. How are leading institutions currently integrating their online platforms with the branch experience to create a frictionless journey for the customer?
The most successful banks in 2026 are those that treat their website and their physical lobby as two doors into the exact same room. We are seeing a trend where the digital onboarding systems used by a customer on their smartphone at home are the identical systems used by a banker sitting behind a desk in the branch. This creates a level of comfort and continuity; if a customer starts an application online and runs into a snag, they can walk into a branch and the employee can pick up exactly where they left off without the customer having to repeat their story. This synchronization is what modern customers demand—they want the speed of digital but the “safety net” of a physical person they can talk to if things get complicated. Investing in best-in-class digital tools while simultaneously rebuilding physical branches ensures that the bank is meeting the customer wherever they happen to be that day.
What is your forecast for the role of the physical bank branch as we move toward the end of the decade?
I forecast that the bank branch will complete its evolution from a place where people go to cash checks to a high-value “consultancy hub” focused on complex financial life events. While daily transactions will move almost entirely to digital and on-chain platforms, the physical branch will become more valuable for securing large-scale loans, navigating business transitions, and building the brand trust that digital-only entities struggle to maintain. We will see more institutions follow the lead of regional powerhouses by reducing their total number of “filler” locations and instead investing heavily in fewer, high-impact “flagship” centers that emphasize community identity. Ultimately, the banks that survive and thrive will be those that use their physical footprint not as a cost center, but as a strategic tool to lower their cost of funds and deepen the emotional connection with their depositors.