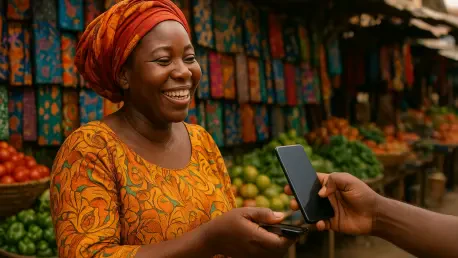
Nigeria’s NIP system currently stands as the only instant payment infrastructure in Africa to reach a fully mature rating for interoperability and governance. This achievement marks a critical milestone in a broader continental shift toward a digitally integrated economy, where high-speed transactions are no longer a luxury but a fundamental requirement for sustainable growth. While the technological foundations are being laid from Cairo to Cape Town, significant hurdles remain that prevent the average citizen from reaping the full benefits of this revolution. At a recent high-level gathering in Nairobi, industry experts and policymakers discussed the complex reality of fragmented networks and the prohibitive costs that continue to sideline millions of Africans. The mission, led by initiatives like the AfricaNenda Foundation, is to move beyond the superficial metrics of mobile phone ownership and focus on deep, inclusive participation. For small-scale entrepreneurs and rural families, the stakes are high; they require a system where the “tap” of a screen translates into immediate, secure value across any platform or border. This evolution is the primary engine for the continent’s modernization, promising to turn basic mobile devices into powerful instruments for individual economic empowerment.
Bridging the Gap Between Access and Usage
The current landscape of digital finance across the continent presents a fascinating paradox where technological availability far outpaces actual economic participation. While the sheer number of mobile devices in circulation suggests a population ready for a cashless future, the reality on the ground indicates that many individuals still operate entirely within the informal, cash-based economy. Bridging this divide requires more than just distributing hardware or building cell towers; it demands a fundamental redesign of how financial services are perceived and utilized by the average person. The transition toward universal inclusion depends on creating environments where digital payments are not just an alternative, but the most logical and cost-effective choice for every daily transaction. Addressing the psychological and logistical barriers to entry is now the primary focus for regional central banks and fintech innovators who are working to ensure that digital tools provide tangible value to the most remote corners of the continent.
The Challenge: Understanding the Participation Deficit
There is a notable disconnect between technology ownership and actual financial participation across the continent that analysts are working hard to bridge. While approximately 75% of African adults own a mobile phone and over half have some form of financial account, nearly 49% of the adult population remains outside the mobile payment ecosystem as of the current 2026 cycle. This “usage gap” suggests that simply providing hardware is not enough to achieve financial inclusion. Many consumers who technically have access to digital tools still choose cash for their daily needs because the digital alternatives feel cumbersome or unreliable.
True progress requires that systems are designed to be intuitive and functional even for those using basic feature phones or living in areas with poor internet connectivity. In many rural districts, the lack of consistent electricity makes smartphone-based apps impractical, pushing the need for more robust USSD-based solutions that can operate on older networks. Inclusion cannot be achieved if the digital economy only serves those with high-end devices and stable data plans. By focusing on the specific needs of low-income users, developers are now prioritizing low-bandwidth interfaces and offline-capable transaction models to ensure no citizen is left behind.
Practical Barriers: Reaching the Last Mile
Reaching the “last mile” remains one of the most significant logistical challenges for payment providers seeking to scale their operations. In many regions, the physical infrastructure necessary to support digital cash-in and cash-out points is still underdeveloped, leaving rural users stranded without a way to convert their digital balance into physical goods or services when needed. This infrastructure vacuum often results in a reliance on informal agents who may charge high fees, further discouraging the use of digital systems. To solve this, providers are experimenting with agent-agnostic networks that allow users to access their funds regardless of which mobile operator or bank they originally signed up with.
Furthermore, the lack of localized digital content and interfaces in native languages remains a silent barrier to mass adoption. For a merchant in a local village market, a payment app that only functions in a secondary language can be intimidating and prone to user error. Innovation is now moving toward voice-activated commands and icon-based navigation to circumvent literacy issues and build confidence among non-traditional users. By removing these practical friction points, the industry is shifting its focus from simple “access” to meaningful “engagement,” ensuring that every transaction reinforces the user’s trust in the digital ecosystem.
Evolution of Financial Infrastructure
The structural modernization of payment networks is currently undergoing a massive overhaul to support the increasing volume of real-time transactions. For years, the plumbing of the financial world was built on slow, batch-processed systems that were never intended to handle the millisecond-fast demands of a modern mobile economy. These legacy frameworks often created bottlenecks that resulted in delayed settlements and high operational overhead for banks. To correct this, national regulators are pushing for the adoption of next-generation infrastructure that supports instant, 24/7 clearing and settlement. This technical shift is essential for creating a reliable environment where merchants can receive funds immediately, allowing them to reinvest in their inventory and manage their cash flow with unprecedented precision.
Technical Evolution: Shifting from Bilateral to Multilateral Networks
The technical architecture of African payment systems is moving away from inefficient “bilateral” arrangements that once dominated the industry. In the past, banks and mobile operators had to create individual, isolated connections with each other, leading to high operational costs and complex legal hurdles that stifled innovation. Every new partnership required a separate technical integration and a unique set of commercial agreements, making it nearly impossible for smaller startups to enter the market. This fragmented approach not only slowed down the deployment of new services but also kept transaction fees high for consumers who were forced to pay for the complexity of the underlying network.
The modern solution is a “multilateral” framework, where a financial institution connects to a single central hub to gain access to all other participants. This “one-to-many” approach levels the playing field, allowing smaller microfinance providers to compete with large commercial banks while lowering costs for the end user. By standardizing the way data is exchanged and transactions are verified, these central hubs reduce the technical burden on individual players. This shift is particularly beneficial for the 2026 to 2028 development window, as it allows for the rapid scaling of interoperable services that can bridge the gap between different mobile money platforms and traditional banking accounts.
Progress Tracking: Benchmarking System Maturity
To track progress accurately, regional systems are assessed based on their maturity, ranging from basic person-to-person setups to fully mature ecosystems. Currently, only Nigeria’s NIBSS Instant Payment (NIP) system has achieved a “mature” rating, serving as a blueprint for the rest of the continent in terms of governance and technical reliability. This rating is not just about speed; it reflects the system’s ability to handle complex merchant payments, government-to-person transfers, and robust consumer protection protocols. Nigeria’s success has demonstrated that with the right regulatory backing, a domestic system can become the backbone of an entire nation’s economic activity.
Most other African systems are still in the early stages of development, lacking the full interoperability or consumer protection mechanisms necessary to reach the highest standard of the maturity framework. This gap highlights the significant work required to upgrade domestic networks into sophisticated, reliable financial hubs that can support the next wave of economic growth. Regulators in countries like Kenya, Ghana, and South Africa are now looking to adopt similar governance models to elevate their own systems. The goal is to move the majority of the continent’s 36 active systems from “basic” to “progressed” or “mature” status within the next few years, ensuring a high standard of service for all users.
Overcoming Economic and Regulatory Barriers
Economic barriers and regulatory inconsistencies continue to serve as the most significant roadblocks to a truly borderless African digital economy. While technology can facilitate the movement of data, the movement of value is often restricted by outdated laws and high currency conversion costs that act as a hidden tax on every transaction. Small businesses, which are the lifeblood of the continent’s economy, are hit the hardest by these inefficiencies, often finding it easier to trade with partners overseas than with their neighbors across a terrestrial border. Overcoming these obstacles requires a coordinated effort between central banks to harmonize their policies and create a unified financial space that encourages regional trade.
Cross-Border Finance: Addressing the High Cost of Fragmentation
Financial fragmentation is most visible in cross-border trade, where a lack of direct integration often forces transactions to be routed through external currencies like the U.S. dollar. This circuitous process results in an estimated $5 billion loss annually due to currency conversion fees and intermediary bank charges. When a merchant in one country tries to pay a supplier in another, the money often travels through a clearinghouse in Europe or North America before returning to the continent. This not only adds unnecessary costs but also extends the time it takes for a transaction to complete, often taking days instead of seconds.
If transaction costs for small-value transfers were reduced to a target of 3%, an additional $1 billion could remain within African households annually, providing a significant boost to local consumption. For small businesses, these high costs act as a major deterrent to regional expansion, effectively stifling the potential of the African Continental Free Trade Area. Reducing these fees is now a top priority for policymakers who recognize that lowering the barrier to entry for cross-border commerce is essential for long-term prosperity. By establishing direct clearing mechanisms between local currencies, the continent can keep more of its wealth within its own borders and foster a more self-reliant economic structure.
Legal Frameworks: Harmonizing Regional Regulations
Creating a unified payment landscape requires more than just technical solutions; it demands a synchronized legal approach across 55 member states. The African Union is currently working to harmonize rules in several priority areas, including licensing, data governance, and anti-money laundering standards to reduce the regulatory burden on fintech companies. Currently, a service provider must navigate a different set of rules for every country they operate in, which significantly increases compliance costs and slows down regional expansion. This patchwork of regulations creates “islands” of finance that are technically capable of connecting but legally restricted from doing so.
By creating a “passporting” system, a service provider licensed in one country could more easily operate in another, fostering a more competitive and innovative market. This regulatory alignment is essential for moving beyond voluntary cooperation toward an enforceable, continental framework that protects consumers while encouraging innovation. Harmonization also involves standardizing how data is protected and shared, ensuring that users have the same rights and protections regardless of where their transaction originates. As these legal frameworks become more aligned, the continent will see a surge in cross-border investment and the emergence of more “pan-African” financial champions capable of serving the entire population.
Security, Trust, and Public Accountability
The rapid acceleration of digital finance has brought security and trust to the forefront of the industry’s agenda. As transactions become instantaneous, the window for detecting and stopping fraudulent activity has shrunk from days to milliseconds, requiring a completely new approach to risk management. Trust is the most fragile component of any financial system; if consumers feel that their money is not safe, they will quickly retreat to the perceived security of physical cash. Therefore, building a secure ecosystem is not just a technical requirement but a social necessity to ensure that the digital transition remains inclusive and sustainable for all segments of society.
Digital Safety: Managing the Risks of Instant Transactions
As transaction speeds increase, so does the “speed of fraud,” making advanced security a top priority for developers and regulators. Instant payments are particularly attractive to criminals because funds can be moved and withdrawn through a series of accounts before the victim even realizes a crime has occurred. To maintain public trust, systems must implement real-time monitoring and artificial intelligence-driven anomaly detection to flag suspicious patterns as they happen. This proactive approach is essential in an era where social engineering and authorized payment scams are becoming increasingly sophisticated and difficult to detect through traditional means.
Furthermore, building robust recourse mechanisms is vital to ensure that victims have a clear path to recovering their funds or seeking justice. Without clear reimbursement policies and accessible customer support, vulnerable populations may remain skeptical of digital finance, preferring the perceived safety of physical cash. Regulators are now mandating that payment providers offer transparent dispute resolution processes that are easy to navigate for non-technical users. By prioritizing consumer protection, the industry is working to create a “safety net” that encourages adoption among those who were previously hesitant to trust their hard-earned money to a digital platform.
Social Responsibility: The Role of Media and Transparency
Public accountability is a vital component of the transition to digital payments, with journalists playing a key role as investigators of the consumer experience. By looking beyond official press releases and government statements, the media can highlight whether digital financial services are actually reaching rural and marginalized communities as promised. A dedicated coalition of journalists is now focusing on the real-world impact of these technologies, questioning whether the reduction in transaction fees is actually being passed on to the end user. This level of scrutiny ensures that the push for “instant” payments does not come at the expense of “inclusive” access.
Transparency in data and governance allows the public to understand the true progress of financial inclusion initiatives. Journalists and civil society organizations are urged to interpret complex financial data from central banks to hold policymakers and private companies accountable. This includes monitoring the actual usage rates among women and youth, who are often the most excluded from traditional systems. By keeping the narrative focused on the human impact of these systems rather than just the total volume of transactions, the media helps ensure that the digital financial revolution remains grounded in the goal of improving the lives of all citizens.
Future Outlook: A Path Toward Integrated Prosperity
The journey toward inclusive instant payments served as a cornerstone of Africa’s broader economic aspirations throughout the current development cycle. It was observed that success was measured not just by the speed of the underlying technology, but by its ability to serve the most vulnerable members of society. By transitioning to multilateral systems, the region successfully began to eliminate the “currency conversion tax” that previously hampered cross-border trade. Moving forward, stakeholders must prioritize the full implementation of the African Union’s regulatory harmonization goals to ensure that the 2026 to 2028 window sees a dramatic increase in interoperable services.
To maintain this momentum, financial institutions and fintech providers should focus on developing “offline-first” technologies that cater to regions with inconsistent connectivity. Additionally, the establishment of a continental fraud-sharing database will be a critical next step in protecting users from increasingly sophisticated cyber threats. By fostering a coordinated effort between the public and private sectors, the continent can ensure that the transition to a digital economy remains secure, affordable, and, most importantly, accessible to every citizen. The ultimate goal remains the creation of a seamless, integrated financial space that empowers every individual to participate fully in the global economy.