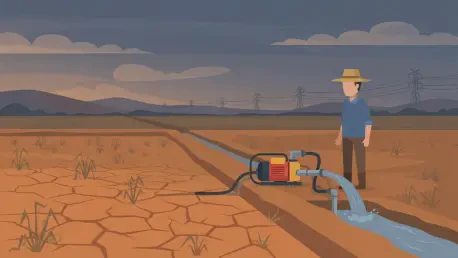
Local businesses like Gerald Soko’s butchery faced ruin as scheduled power cuts, triggered by ZESCO’s insolvency, led to rotting inventory and a vanishing customer base. This specific instance of micro-economic despair reflects the broader story of Zambia’s economic struggle through the eyes of its people, such as Kanangwa Newlove, a commercial farmer whose livelihood collapsed due to a failing national power grid. In late 2025, her organic farm near Lusaka suffered a total loss when the electricity required to pump water for her crops ceased to function. This failure of infrastructure was not an isolated event but rather a symptom of a larger national crisis rooted in the decay of vital infrastructure. The failure of the energy sector was directly tied to the fiscal health of ZESCO, the state-owned power utility, which found itself drowning in debt. While a severe drought in 2024 acted as a catalyst for the power generation shortage, the underlying instability was caused by massive, opaque loans owed to Chinese financial institutions like the Industrial and Commercial Bank of China. These financial obligations prevented the utility from maintaining the very infrastructure the country relies on for survival, leading to a cascade of failures that reached every corner of the Zambian economy.
The Investigative Framework: Analyzing the China Capital Project
Part 1. The Role of International Financial Institutions
The ICIJ investigation, widely known as the “China Capital” project, focuses heavily on the London-based operations of the Industrial and Commercial Bank of China, which served as a pivotal agent for the Belt and Road Initiative across the African continent. Internal documents reveal that while these entities presented themselves as standard commercial banks, their lending patterns were largely dictated by the strategic and geostrategic goals of the Chinese state rather than pure market logic. This alignment allowed for the funding of massive infrastructure projects that traditional Western lenders or the IMF would have deemed far too risky for a developing economy with a fluctuating currency. By operating through a London subsidiary, the bank was able to project an image of international compliance while effectively acting as a financial arm for Beijing’s expansionist foreign policy.
The “muscular lending” strategy employed by these institutions meant that the credit offered was often tied to specific geopolitical outcomes, creating a dependency that was difficult for the Zambian government to manage once economic conditions shifted. Analysts who examined the leaked dossiers found that the bank’s internal risk assessments frequently highlighted the potential for insolvency in Zambian state-owned enterprises, yet the loans were approved anyway. This suggests that the primary objective was not necessarily the successful repayment of the principal through project revenue, but the establishment of long-term influence over Zambia’s critical national assets. This approach fundamentally changed the nature of sovereign debt in the region, replacing the traditional developmental model with a more aggressive, state-backed commercial framework that prioritized the interests of the lender above the economic health of the borrower.
Part 2. Circular Economies and Contractor-Facilitated Lending
A recurring theme highlighted in the “China Capital” investigation is the elaborate ecosystem of “contractor-facilitated lending,” where Chinese banks provided funds for projects that were specifically designed and built by Chinese firms. This arrangement ensured that the vast majority of the loaned capital remained within the Chinese economy, as it was paid directly to the construction and engineering firms involved in the projects. Meanwhile, the entirety of the debt burden, along with the interest and the responsibility for maintenance, was placed squarely on the Zambian government and its taxpayers. This circular flow of money created a system where the lender and the builder were essentially two parts of the same state apparatus, working in tandem to export China’s industrial overcapacity while securing future revenue streams from sovereign debt.
This model of development effectively bypassed traditional competitive bidding processes, leading to inflated project costs and a lack of transparency regarding the quality of the infrastructure being built. Because the financing was so closely tied to the contractors, the Zambian government often found itself in a position where it could not hold the builders accountable for shoddy work without risking its relationship with the bank. This created a moral hazard where the Chinese firms were incentivized to complete projects quickly and move on to the next one, leaving Zambia with expensive assets that often required immediate and costly repairs. The structural integrity of these arrangements ensured that the economic benefits were heavily skewed toward the provider, leaving the host nation to navigate the long-term consequences of maintaining infrastructure that it could barely afford to build in the first place.
The Genesis of a Debt-Fueled Infrastructure Boom
Part 1. Transitioning from Debt Relief to Modernization
In 2011, Zambia stood in a unique and enviable position among African nations, having benefitted significantly from prior international debt relief programs that left the country largely debt-free. With a clean balance sheet and a growing middle class, the government felt a strong mandate to pursue rapid modernization and close the country’s significant infrastructure gap. Seeking to capitalize on this optimistic outlook, the government aggressively tapped into international capital markets, issuing billions of dollars in sovereign bonds between 2012 and 2015. This period of high liquidity and investor confidence provided the initial spark for an appetite for expansion that would eventually become unsustainable. The goal was to transform Zambia into a regional hub for trade and energy, but the speed of this transition far outpaced the government’s capacity for oversight and fiscal management.
This intense desire for rapid growth coincided perfectly with China’s strategic push to export its construction capacity and secure access to raw materials through the Belt and Road Initiative. For Zambian officials, the Chinese proposal was the missing piece of the puzzle, providing the necessary capital and technical expertise to build roads, bridges, and power plants at an unprecedented scale. However, the move away from cautious, multilateral developmental aid toward high-interest commercial debt was a gamble that relied on the continued high price of copper and a stable global economy. As the government shifted its focus toward these massive “showpiece” projects, it began to move away from the disciplined fiscal path that had been established during the debt relief era, setting the stage for a future where debt servicing would eventually consume the majority of the national budget.
Part 2. The Appeal of Paternalism-Free Credit
Chinese lenders successfully marketed themselves as a more flexible and respectful alternative to traditional Western institutions like the World Bank or the IMF. These Western organizations typically demand strict policy reforms, transparency measures, and austerity programs in exchange for financial support, which can be politically difficult for local leaders to implement. In contrast, the “easy” credit offered by Beijing was highly attractive to the Zambian government because it came with fewer strings attached regarding domestic policy or internal governance. This narrative of a “partnership of equals” allowed Zambian politicians to frame the borrowing as a sign of national sovereignty and a rejection of Western paternalism, even as the terms of the loans were becoming increasingly lopsided in favor of the lender.
The lack of rigorous policy conditions meant that loans were often granted without comprehensive feasibility studies or assessments of whether the infrastructure could generate enough revenue to be self-sustaining. This absence of oversight was a double-edged sword; while it allowed for the rapid commencement of projects, it also meant that the Zambian state was taking on enormous risks without a clear plan for repayment. By the time the government realized the true cost of this “condition-free” credit, the debt had already ballooned to levels that threatened the stability of the entire economy. The perceived flexibility of Chinese lending ultimately masked a more rigid and unforgiving financial reality, where the lack of upfront policy requirements was replaced by aggressive recovery tactics once the country’s ability to pay began to falter under the weight of its obligations.
The Mechanics of Persistent Debt Accumulation
Part 1. Outsourcing the Financing Process
The institutionalization of debt within the Zambian state was frequently led by the Chinese construction firms themselves, who took on the role of intermediaries between the government and the mega-banks in Beijing. For instance, a major power infrastructure project worth hundreds of millions of dollars was essentially brokered by the very firm that won the contract to build the transmission lines. These firms would approach Zambian ministries with “pre-packaged” deals that included both the technical plans and the financing options, making it incredibly easy for officials to sign off on massive projects without consulting the central treasury or independent financial advisors. This effectively outsourced the nation’s financial planning to foreign contractors whose primary interest was securing the next contract rather than ensuring the country’s long-term fiscal health.
This decentralized approach to borrowing led to a situation where different government departments were taking on debt independently, resulting in a lack of a unified national debt strategy. Zambia ended up hosting a disproportionately high number of Chinese contractors compared to its neighboring countries, as each ministry sought to secure its own “legacy” projects through these streamlined financing channels. The ease with which these deals were made bypassed traditional checks and balances, allowing for the accumulation of liabilities that were often hidden from the public and even from international monitors. By the time the total scale of the borrowing was recognized, the sheer number of individual agreements and the complexity of the “contractor-facilitated” model made it nearly impossible to implement a cohesive plan for debt management or to slow down the rate of accumulation.
Part 2. The Barrier of Confidentiality Clauses
One of the most significant obstacles to managing the Zambian debt crisis was the extreme opacity of the loan agreements, which almost universally contained far-reaching confidentiality clauses. These legal provisions prohibited the Zambian government from disclosing the specific terms, interest rates, or repayment schedules to other international creditors, including the IMF and the Paris Club. This culture of secrecy was a standard requirement for Chinese state-backed loans, and it served to mask the true scale of the nation’s liabilities for years. When independent researchers and international organizations finally began to piece together the puzzle, they discovered that the actual debt was nearly double what the Zambian government had officially reported in 2021, revealing a massive gap in the public’s understanding of the country’s financial position.
The presence of these clauses created a environment of mistrust between Zambia and its other developmental partners, who were hesitant to provide additional aid or debt relief without knowing the full extent of the country’s obligations to China. This lack of transparency also prevented the Zambian parliament and civil society from performing their oversight duties, as they were legally barred from reviewing the contracts that were mortgaging the country’s future. The confidentiality requirements were not just a legal technicality; they were a strategic tool that allowed the debt to grow in the shadows, far away from the scrutiny of the market or the public. This structural secrecy meant that by the time the crisis became undeniable, the lack of clear data hampered the ability of the government to negotiate a fair and timely restructuring of its debt, prolonging the economic pain for the average citizen.
Aggressive Tactics in Debt Recovery
Part 1. The Myth of Brotherly Solidarity
When the Zambian economy began to show undeniable signs of distress, the high-minded rhetoric of “win-win” cooperation and “brotherly” solidarity from Chinese lenders was quickly replaced by hard-nosed financial maneuvers. Internal records from the “China Capital” investigation show that even as Chinese officials were publicly praising their partnership with Zambia, their banks were moving behind the scenes to protect their own interests at the expense of the host nation. Despite having full knowledge that state-owned entities like ZESCO were practically insolvent, Chinese financial institutions did not offer the flexibility or grace periods that the “partnership” narrative would have suggested. Instead, they employed aggressive tactics to ensure that their payments remained a priority, even as the Zambian people began to suffer from the collapse of basic services.
This shift in behavior highlighted the fundamental reality that these were not developmental loans in the traditional sense, but commercial agreements backed by the full power of the Chinese state. The priority was never the long-term economic stability or social welfare of Zambia, but the guaranteed recovery of the loaned capital and the protection of the lender’s balance sheet. This aggressive stance often put Chinese banks at odds with other international creditors who were attempting to find a more sustainable and collaborative way to manage Zambia’s default. The myth of a different, more compassionate kind of lending was shattered as the banks prioritized debt recovery above all else, demonstrating that when the financial stakes are high, the strategic interests of the lender will always outweigh the humanitarian needs of the borrower.
Part 2. The Use of Escrow Accounts for Seizure
A critical and often overlooked tool in these lending agreements was the mandatory use of reserve or “escrow” accounts, which provided the lender with direct and unilateral control over a significant portion of the borrower’s funds. These accounts were typically held in jurisdictions outside of Zambia, such as London or Beijing, and were funded by the revenues generated by the projects themselves or by general government funds. Under the terms of the contracts, Chinese banks had the right to seize money from these accounts to cover missed payments without ever having to seek permission from the Zambian government or participate in standard debt negotiation protocols. This “self-help” mechanism allowed the banks to bypass the collective restructuring efforts sought by other international creditors and ensured they were the first to be paid.
By acting as their own escrow agents, Chinese banks maintained a level of leverage that traditional multilateral lenders simply did not have. This capability allowed them to drain vital foreign exchange reserves from the Zambian economy at the very moment the country needed those funds to stabilize its currency and pay for essential imports like food and medicine. This “hardball” approach fundamentally undermined Zambia’s ability to navigate its worsening financial position, as it stripped the government of the liquidity needed to address internal crises. The use of these accounts turned what should have been a collaborative debt management process into a series of unilateral seizures, further complicating the country’s path to recovery and ensuring that the financial impact of the debt was felt most acutely by the Zambian public rather than the lenders.
The Convergence of Financial and Environmental Crises
Part 1. The 2020 Default and Currency Devaluation
Zambia’s economic journey reached a disastrous turning point in 2020 when it became the first African nation to default on its sovereign debt during the height of the global pandemic. This collapse was the culmination of years of fiscal mismanagement, a steady decline in the global price of copper, and the sheer weight of its foreign-denominated debt. As investors lost confidence, the national currency, the kwacha, experienced a massive and rapid devaluation, making the cost of servicing loans denominated in US dollars or Chinese yuan nearly impossible. This financial tailspin had an immediate and devastating impact on the cost of living for ordinary Zambians, as the price of imported goods skyrocketed and runaway inflation eroded the purchasing power of their wages.
The devaluation of the currency created a vicious cycle where the government had to spend more and more of its dwindling revenue just to keep up with interest payments, leaving almost nothing for social services, healthcare, or education. Local businesses found themselves unable to access credit as interest rates surged to prohibitive levels, and many were forced to close their doors. This default was not just a technical failure of the treasury; it was a national trauma that signaled the end of a decade of hope and the beginning of a long and painful era of austerity. The financial collapse laid bare the vulnerability of an economy that had been built on a foundation of debt and a single commodity, proving that the modernization boom was far more fragile than the government had ever admitted to its people.
Part 2. The Catastrophe of Load Shedding
The financial insolvency of ZESCO, the national power utility, directly led to one of the most visible and damaging aspects of the crisis: the implementation of “load shedding,” or scheduled and erratic power cuts that lasted for hours or even days. Because the utility was drowning in debt owed to Chinese banks and contractors, it lacked the necessary funds to maintain its existing power plants or to diversify its energy sources away from a total reliance on hydropower. This lack of financial buffer meant that the utility was completely defenseless when a massive and historic drought hit the region in 2024. Without enough water to turn the turbines and no money to import emergency power from neighboring countries, the national grid began to fail, plunging homes and businesses into darkness and crippling the economy.
The energy crisis was a direct consequence of the debt-fueled infrastructure strategy that had prioritized large-scale hydropower projects over more resilient and diversified energy systems. Small and medium enterprises, which form the backbone of the Zambian economy, were hit the hardest as they could not afford the expensive diesel generators needed to maintain operations during the cuts. For many, the lack of reliable power was the final blow after years of economic hardship. This catastrophe demonstrated how high-level sovereign debt can translate into a total failure of basic infrastructure, showing that the “assets” built during the boom were of little use if the state could not afford to keep them running. The darkness in Zambia’s cities and towns became a powerful and enduring symbol of the country’s broader financial and structural paralysis.
Evolving Trends in Chinese-African Relations
Part 1. The Shift Toward Small and Beautiful Projects
The profound fallout in Zambia has prompted a significant and visible shift in Chinese foreign lending policy, not just in Lusaka but across the entire African continent. Recognizing the reputational damage and the financial risk associated with massive, unsustainable infrastructure projects, Beijing has moved away from the “blank check” era. In its place, a new strategy known as the “small and beautiful” approach has emerged, focusing on smaller, more manageable projects that have shorter repayment periods and more rigorous risk assessments. This shift indicates a growing awareness that the previous model of aggressive, state-backed commercial lending was creating more long-term problems than it solved, leading to defaults that were becoming a burden for the Chinese financial system as well.
This new era of lending is characterized by a greater emphasis on project viability and social impact, as well as a more cautious approach to sovereign risk. Projects that are approved in the 2026 to 2028 period are likely to be more focused on technology, telecommunications, and green energy, rather than the massive dams and airports of the previous decade. While this change is a positive step toward more sustainable development, it also means that the “easy money” that fueled Zambia’s boom has largely disappeared, leaving many other developing nations to find alternative ways to fund their infrastructure needs. For Zambia, this shift came too late to prevent the crisis, but it serves as a critical lesson for the rest of the continent about the dangers of unchecked debt and the importance of fiscal discipline in international partnerships.
Part 2. A Decline in Public Perception
There has been a documented and significant decline in how the Zambian public views Chinese influence within their borders, moving from a position of cautious optimism to one of widespread skepticism and resentment. Survey data collected over the last decade shows that positive sentiment toward China has dropped sharply as the perception of the relationship has shifted from one of developmental partnership to one of predatory lending. The local population increasingly views the massive infrastructure projects built during the boom—many of which are now crumbling or underutilized—as symbols of the debt that has stifled their economic growth and limited their children’s future. This change in public opinion has had a significant impact on Zambian politics, making the country’s relationship with China a central and contentious issue in national elections.
This cooling of relations is not just limited to the halls of government; it is felt on the streets, where Zambian workers and small business owners often feel they have been sidelined by Chinese firms and labor. The initial promise of job creation and technology transfer has, in many cases, failed to materialize, leading to a sense of exploitation rather than cooperation. As the 2026 to 2028 economic recovery plan continues, the government must navigate this public anger while still maintaining a functional relationship with its largest creditor. The decline in public perception serves as a stark reminder that infrastructure alone is not enough to secure a positive international legacy; if the financial and social costs of that infrastructure are too high, the resulting resentment can last for generations and fundamentally alter a nation’s geopolitical alignment.
A Synthesis of the Zambian Debt Spiral
Part 1. The Combination of Ambition and Failure
The tragedy of the Zambian financial crisis was the product of three powerful and converging forces that created a perfect storm of economic instability. First was the aggressive geostrategic ambition of the Chinese state, which sought to expand its influence and secure markets for its firms through a model of muscular and often reckless lending. Second was the internal failure of Zambian governance, where a leadership more focused on political showmanship and short-term gains than on sustainable planning allowed the country to take on debt it could never realistically service. Finally, the extreme environmental volatility brought on by climate change and the fluctuation of global commodity prices acted as the final catalyst, exposing the fragility of a system that had been built without any margin for error or economic resilience.
These three factors worked in tandem to create a spiral that was nearly impossible to break once it had begun. The ambitious infrastructure projects provided the political cover for the borrowing, while the lack of transparency ensured that the growing danger remained hidden from the public eye. When the environmental and market shocks arrived, the country was already so overleveraged that it had no tools left to respond. This was not a failure of a single policy or a single actor, but a systemic collapse that demonstrated the profound danger of combining high-level sovereign debt with weak institutional oversight and an over-reliance on a single export. The synthesis of these forces provides a definitive and cautionary account of how a nation’s future can be mortgaged for the sake of immediate but unsustainable growth.
Part 2. The Long-Term Cost of Opaque Finance
In retrospect, the Zambian government’s decision to embrace opaque, high-interest financing was a gamble that ultimately cost the nation a decade of lost economic potential and the near-collapse of its middle class. While the physical infrastructure built during the boom—the roads, the airports, and the power lines—remains as a testament to that era, the financial burden required to keep them has become a weight that will take years to fully lift. The “China Capital” investigation has shown that for other developing nations, the primary lesson of the Zambian experience is the vital importance of transparency and the need for independent oversight in all international lending agreements. Moving forward, the focus must shift toward building resilience through diversified energy sources, such as solar and wind, and ensuring that any new debt is subject to the highest levels of public scrutiny and competitive bidding.
The actionable next steps for Zambia and its neighbors included the implementation of more robust legal frameworks that prohibited confidentiality clauses in sovereign debt and the creation of independent debt management offices that operated outside of political influence. By the end of 2025, the transition toward a more transparent and sustainable financial model began to show the first signs of success, although the scars of the previous decade remained visible in the daily lives of citizens like Gerald Soko and Kanangwa Newlove. The hard-earned insights from this crisis emphasized that true modernization cannot be bought with easy credit; it required the slow and steady work of building strong institutions, fostering a diversified economy, and ensuring that the benefits of development were shared by all rather than being concentrated in the hands of a few contractors and lenders. The legacy of this period served as a blueprint for a more cautious and resilient approach to global finance in the years that followed.